Explore
What policies generally say — and what only yours can settle.
Everything here describes what many standard forms say, not what your policy says. Outcomes vary with the state, the form edition and the endorsements attached, so your own policy and state rules control.
- Free to browse
- Clause headings named
- Primary sources listed
Browse the question library
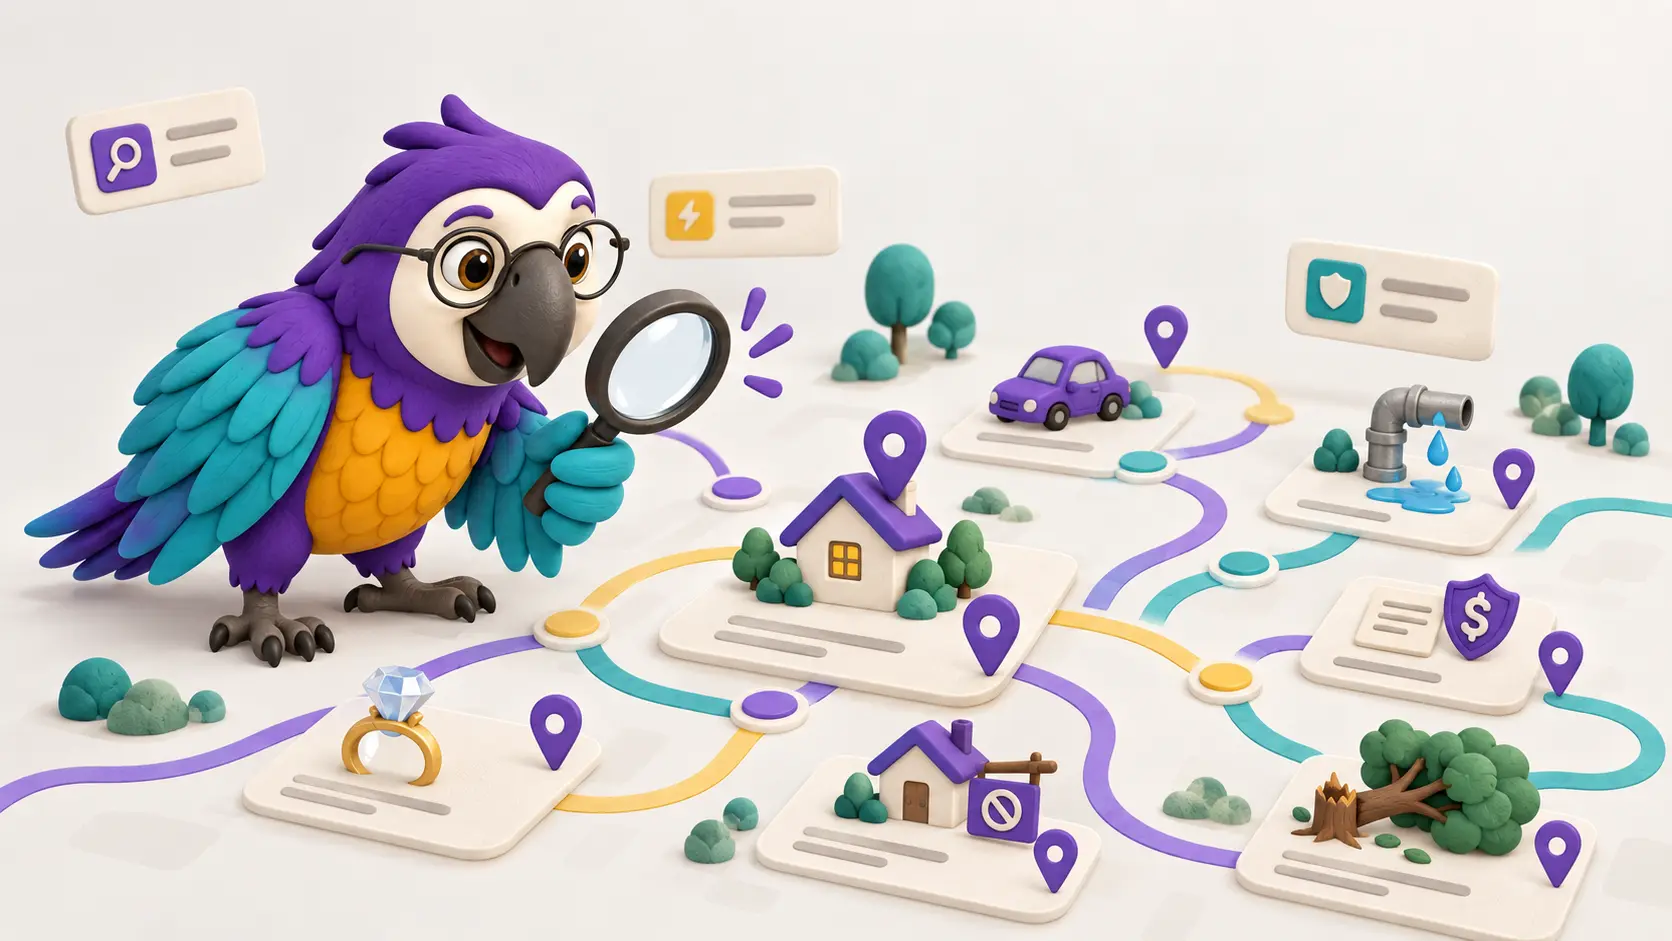
Each page gives the general answer, why your policy can read differently, and the clauses to look for. Filter by policy type or search for the situation you are in.
Home
Does homeowners insurance cover a tree falling on my fence?
Filed homeowners forms usually treat a fallen tree and the fence it landed on under different clauses. Here is what to look for — then read your own policy.
Home
Does homeowners insurance cover a slow plumbing leak?
A pipe that bursts today and a pipe that's been dripping for months are treated very differently. Here's the wording that decides which one you have.
Home
Is stolen jewelry covered by homeowners insurance?
Jewelry is usually covered, but under a special dollar cap that is far below the personal-property limit. Here is where to find yours.
Home
What happens if my house is vacant for 60 days?
Vacancy clauses suspend or reduce coverage after a set number of consecutive days. The number is in your own form.
Home
Does insurance pay to haul away debris after a covered loss?
Debris removal is usually its own clause with its own limit rather than part of the main coverage amount.
Home
Will insurance pay for code upgrades when I rebuild?
Bringing a repair up to current building code is usually excluded, then partly restored by an ordinance-or-law clause with a fixed cap.
Home
Why is my wind and hail deductible different from my regular deductible?
Many policies apply a separate percentage deductible to wind and hail losses instead of the flat dollar amount on the declarations page.
Home
Replacement cost or actual cash value — which one will I be paid?
Loss settlement clauses decide whether depreciation comes out of your payment, and a coinsurance condition can reduce it further.
Home
Does homeowners insurance cover water backing up into the basement?
Backup through a drain or sewer is usually handled by an endorsement with its own limit, not by the main water clauses.
Home
Is mold covered after a covered water leak?
Mold is often limited to a fixed dollar amount even when the water that caused it was covered.
Home
Will insurance pay for a hotel while my house is repaired?
If your home isn't livable, the policy may help pay for a hotel or rental — up to a set dollar amount and for a set length of time.
Home
Does homeowners insurance cover a dog bite?
Bites are usually a liability question, and breed or prior-incident wording can remove coverage entirely.
Home
Why did my roof claim pay less than the repair estimate?
Roof settlement is frequently moved to a depreciated or scheduled basis by endorsement even when the rest of the dwelling is on replacement cost.
Home
How long do I have to report damage to my insurer?
Most forms require prompt notice rather than a fixed number of days, and late notice is a common reason for denial.
Home
Is my home-office equipment covered by my homeowners policy?
Business property in the home is normally covered only up to a small cap, and business liability is usually excluded.
Home
Who counts as insured on my homeowners policy?
The definitions section decides which household members and relatives are covered, and it rarely matches who lives there.
Home
Does homeowners insurance cover hurricane damage?
Most homeowners forms cover hurricane wind, but not hurricane flooding, and many apply a separate, larger hurricane deductible. Here's where each piece lives in your policy.
Home
Does homeowners insurance cover nor'easter damage?
Most homeowners forms treat a nor'easter's wind and its coastal flooding very differently. Wind is usually a covered peril; storm surge and flood water usually are not. Here's where each piece lives in your policy.
Home
Does homeowners insurance cover roof damage from a storm?
Storm roof claims usually turn on three things: what caused the damage, how old the roof is, and which deductible applies. Here's where each one lives in your policy.
Home
Does homeowners insurance cover flooding?
Filed homeowners forms exclude flood, but they cover several kinds of water that people call flooding. The distinction lives in one exclusion paragraph.
Home
Is rain that blew in through my window or roof covered?
Most forms cover rain inside the building only after wind first made an opening. Whether your policy says that can materially affect how it responds.
Home
Why was my hail-damaged roof called cosmetic?
A growing number of policies add an endorsement that pays for hail damage only when it affects how the roof functions, not how it looks.
Home
Does homeowners insurance cover ice dam damage?
Weight of ice is usually a named peril, but the repeated-seepage exclusion and the roof-maintenance exclusion often meet the same claim.
Home
Will insurance pay to match my undamaged siding or shingles?
Most forms pay to repair what was damaged, not to make the whole elevation match. A few clauses decide how far the repair extends.
Home
Why did my homeowners insurance go up when I had no claims?
Most renewal increases show up as changed numbers on the declarations page rather than as a rate notice. Here is what to compare.
Home
What does it mean when my insurer non-renews my policy?
Non-renewal and cancellation are different clauses with different notice requirements, and the policy spells both out.
Home
Why did my dwelling coverage go up on its own?
An automatic increase provision adjusts Coverage A each term, and several other numbers in the policy move with it.
Home
What are wind mitigation credits and are they on my policy?
In coastal states, roof and opening features can earn premium credits. They appear on the declarations page, not in the booklet.
Auto
Is someone else covered driving my car?
Usually yes, if you let them drive it. Car insurance mostly follows the car, not the driver — but whether you gave permission, and who lives in your house, is what settles it.
Auto
Does my auto policy pay for a rental car while mine is repaired?
Rental reimbursement is usually a separate purchased coverage with a daily cap and a total cap, not something liability or collision includes. Here is where to check.
Auto
Do I pay a deductible for a cracked windshield?
Say a rock chips your windshield on the highway. That's usually a comprehensive claim, so your comprehensive deductible applies — unless your policy added glass coverage that lowers or removes it.
Auto
What does uninsured motorist coverage actually pay for?
UM and UIM cover what the other driver should have paid you and could not. The limits, the stacking rules and the property-damage piece are all separate questions.
Auto
Am I covered driving for DoorDash, Uber, or Instacart?
Nearly every personal auto form excludes carrying people or property for a fee. Here is the exclusion and the endorsement that changes it.
Auto
How does my insurer decide my car is totaled and what it is worth?
Most forms pay actual cash value or repair cost, whichever is less — which is why a repairable car gets totaled. Here is the wording that sets the number.
Auto
Is hail damage to my car covered?
Hail is a comprehensive loss on most auto forms — which means it is only covered if you bought comprehensive. Here is where that shows up.
Auto
What is the difference between medical payments and PIP on my auto policy?
Both pay injury costs regardless of fault, but they cover different things and are required in different states. Here are the clauses to compare.
Auto
If I cause an accident, what does my policy actually pay?
Liability pays the other party, collision pays your own car, and each is capped separately. Here is how filed forms divide it.
Auto
My car was stolen — what does the policy cover?
Theft is normally a comprehensive claim, with rules about waiting periods, personal belongings and how value is settled.
Auto
Who pays the gap between my loan balance and the car's value?
A standard auto policy pays value, not the loan. Gap or loan/lease coverage is the endorsement that closes the difference.
Auto
A hit-and-run driver damaged my car — which coverage responds?
Depending on the form and state, this lands under collision or uninsured motorist property damage. The distinction changes your deductible.
Auto
Does my policy follow me into a rental car?
Most forms extend coverage to a temporary substitute or non-owned auto, but the terms are narrower than the counter agent's pitch implies.
Auto
Does my teenager need to be listed on the policy?
Resident relatives are usually insureds whether listed or not — but listing is what keeps the rating honest and the claim uncontested.
Auto
Is flood or water damage to my car covered?
Comprehensive normally covers flooded vehicles — one of the places auto coverage is broader than a homeowners policy.
Auto
Is hitting a deer collision or comprehensive?
Animal strikes usually fall under comprehensive, which matters because the deductibles are often different.
Auto
Am I covered using my personal car for work errands?
Ordinary commuting is normally fine; carrying goods or people for a fee is where filed forms push back.
Auto
Does my policy cover towing and roadside assistance?
Towing and labor is a small optional coverage with tight limits, and it usually only pays labor performed at the disablement site.
Auto
I got rear-ended at a red light — whose insurance pays?
Say you're stopped at a red light and the car behind you rolls into your bumper. The other driver's liability coverage is usually the first place the repair bill goes — your own policy has backups if they have no insurance or won't pay.
Auto
A shopping cart dented my car door — is that covered?
A loose cart rolling into your parked car is a classic small claim. Most policies treat it as collision or comprehensive depending on how the form defines it — and the repair is often less than the deductible.
Auto
I hydroplaned into a guardrail — what does my policy cover?
Sliding on a wet road into a guardrail is usually a collision claim for your car. If the guardrail is damaged, the state may bill you — and that bill usually goes to your liability coverage.
Auto
Can I claim the value my car lost after being repaired?
Diminished value is usually excluded from your own physical damage coverage, and treated very differently when someone else was at fault.
Auto
What happens to a claim if my premium payment was late?
Coverage generally turns on whether the policy was in force at the moment of loss, and cancellation notice rules are set by state law.
More from Poli
Open a section to read the upkeep notes and the what-ifs people actually bring to Poli.
Where this comes from
Primary sources
General statements on this page are drawn from publicly filed standard forms, regulator material, and federal program documents. None of it is a determination about your policy.
- NAIC — homeowners and auto consumer material
Regulator-published explanations of standard coverage parts, adjuster roles, and consumer rights.
- Georgia Office of Insurance Commissioner
State-level rules, bulletins, and consumer guidance. Other states publish their own equivalents.
- NFIP / FloodSmart
Federal flood program terms, which sit outside most homeowners forms.
- FEMA flood insurance policy documents
The actual Standard Flood Insurance Policy wording and program manuals.
- Insurance Information Institute
Industry reference material on how standard forms are typically structured.
- CFPB / state DOI complaint channels
Where to take a dispute. PoliSays does not represent you or negotiate on your behalf.
PoliSays explains document wording. It is not an insurer, broker, adjuster, or law firm, and nothing here is advice, a coverage determination, or a claim valuation.
General wording only goes so far.
Upload your policy and Poli quotes the clause that settles your question.
It only takes a minute. Nothing is stored unless you save it.